

 China’s Chipmaking Equipment Industry Faces Shake-Out After Players Multiply, Insiders Say
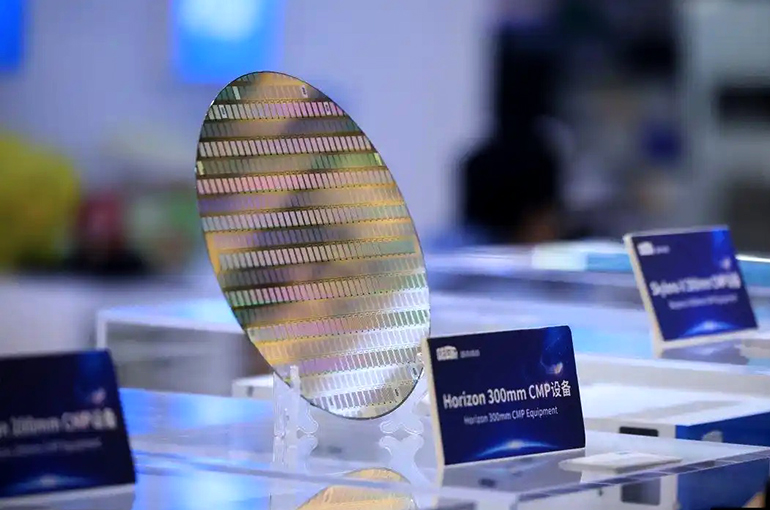
(Yicai) Nov. 18 -- US-led restrictions on semiconductor equipment exports to China have hastened the growth of China’s own chipmaking equipment industry, but the resulting influx of manufacturers has created an overcrowded market ripe for consolidation, according to insiders.
Dozens of domestic firms are developing and producing key equipment for every process in the semiconductor equipment sector, with no major differences between their products, Wang Zhiyue, secretary-general of the China Electronic Production Equipment Industry Association, told Yicai. “Every type of equipment used in every process is crowded with developers,” he said.
Even in the relatively less crowded lithography machine market, there are around 10 developers, Wang noted, adding that other areas often have more than 10 or even 20 competing firms.
China’s semiconductor equipment is entering a new era of domestic substitution, Wu Kai, executive deputy secretary-general of the Semiconductor Equipment, Materials and Core Components Exhibition’s organizing committee, told Yicai.
“Opportunities are basically equal for everyone,” Wu said. “With access to capital and technological resources, anyone can start a business, creating a situation where dozens of companies compete within one product category.”
Most of these companies offer similar technology and products, making it hard to avoid cutthroat competition, Wang stressed, noting that firms use every competitive trick, such as price wars and aggressive scrambles for supply chain resources.
The homogeneity is particularly pronounced in back-end equipment, used for process such as packaging and testing, Wang said. The front-end equipment segment has higher barriers to entry and fewer overlapping offerings, thanks to massive investment and longer research and development cycles, Wang added.
Shake-Out Is Inevitable
Nevertheless, Wu said that such a phenomenon is normal at this stage. Because China’s semiconductor equipment industry has a short history, many players had to enter the space to break the foreign monopoly, Wu noted, pointing out that overseas players followed a similar development path in the past.
Signs of industry consolidation are already emerging. Naura Technology Group took a controlling stake in Kingsemi in May and began fully acquiring Beijing Nuohe Jianwei Equipment last month, while Advanced Micro-Fabrication Equipment bought a controlling stake in Hangzhou Sizone Electronic Technology, also in May.
Consolidation is inevitable, according to Yin Zhiyao, chairman of AMEC. A fragmented, “every-man-for-himself” approach cannot succeed in this competitive landscape, he noted.
The industry’s development model will shift from the “catch-up” phase that defined the past two decades toward a focus on independent innovation over the next 20 years, Yin pointed out. The goal is not only to catch up with peers abroad, but also to surpass international state-of-the-art standards in technology and overall performance, he added.
The industry can navigate its way through the “growing pain” period over the next three to five years, Wang said. Each of the top three companies in each equipment sub-category can gain a clear competitive advantage over rivals, Wang stressed.
Semiconductor equipment mainly includes lithography machines, etching machines, thin-film deposition equipment, cleaning equipment, and packaging equipment. Each category has several sub-categories, with lithography machines the most critical gear.
Since the United States imposed export controls on advanced chips and equipment to China, leading Chinese companies such as AMEC and Naura have grown but still lag behind their overseas peers in scale and technological capabilities.
Editors: Tang Shihua, Martin Kadiev