

 China’s Central Bank Boosts Liquidity via MLF; Monetary Policy Won’t Change Soon, Analysts Say
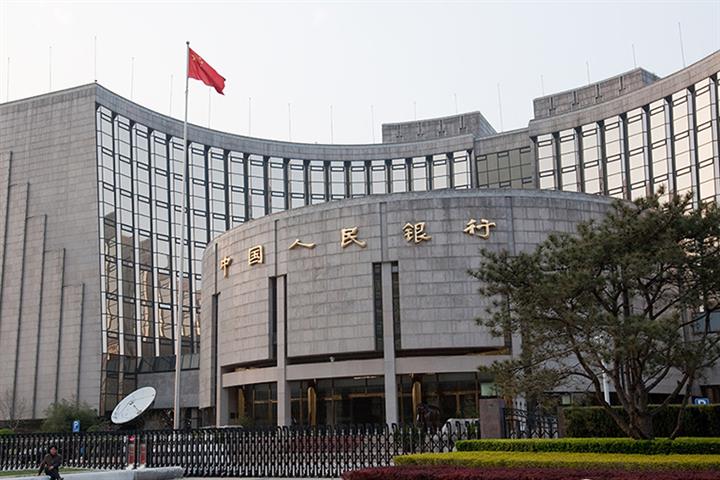
(Yicai Global) Dec. 16 -- The People's Bank of China infused an extra CNY150 billion (USD21.5 billion) into the banking system yesterday via medium-term lending facility loans to keep liquidity ample at year end. The central bank is unlikely to make any drastic changes to monetary policies in the near term, analysts said.
The PBOC injected CNY650 billion (USD93.2 billion) of fresh funds into the financial system through renewed one-year MLF loans, a CNY150 billion increase on the CNY500 billion that matured that day, and CNY2 billion (USD287 million) in seven-day reverse repurchase operations. This follows a 25-basis-point cut in banks’ reserve requirement ratio on Dec. 5.
The PBOC's liquidity boost is a signal that monetary policy will not change direction in the near future, said Chen Jianheng, director of fixed-income research at China International Capital Corporation's research department. It will also help repair confidence and spur demand in the bond market.
The PBOC tends to increase the size of its MLF loans when the economy is under pressure or when there are risks in liquidity and the credit market, said Chen. For instance, in the early stages of the Covid-19 pandemic, between January 2020 and March 2020, the central bank injected an additional CNY600 billion into the open markets through MLF loans so as to providing medium-and long-term funds to relieve panic about the market and liquidity.
It is crystal clear that the PBOC intends to keep liquidity in the banking system abundant and relatively loose, said Zhang Xu, chief fixed-income analyst at Everbright Securities. The higher-than-expected MLF loan injection highlights the central bank's intention of keeping the bond market stable.
There is unlikely to be a big change in PBOC’s policy direction next year, even if the economy rebounds, Chen said. This is because a premature shift in direction will affect the momentum of economic recovery.
In the past, the PBOC tightened policy to curb overheated demand, Chen said. If the economy bounces back to a level where supply and demand are balanced and inflation is within target, then there is unlikely to be noticeable tightening of policy.
Editors: Shi Yi, Kim Taylor